

Catch-22 | To Increase the Prices or Reduce the Margin ?
Whether you are a business owner , CXO or Brand Owner - its time to think about this question and - prepare - before - panic - sets in ...
“In every disruption, the first movers write the new rules. The fast followers survive. The wait-and-see players explain what they could have done.” — BMCG Strategic Brief, March 2026
Somewhere in a boardroom in Mumbai, a CFO is staring at a spreadsheet that no longer makes sense.
Her input costs are up 25–30%. Freight has doubled. The rupee is slipping. And her consumers — still carrying the bruises of two years of inflation — are already hunting for cheaper alternatives.
She faces the oldest, sharpest dilemma in business:
Do you raise prices? Or do you quietly eat the margin and hope the world calms down?
Welcome to the Catch-22 of 2026.
There is no easy answer. But there is a strategic answer. That’s what this piece is about.
🔥 How War Is Reshaping Energy, Capex, and Global Trade
Everything traces back to one narrow strip of water.
The Strait of Hormuz. 50 kilometres wide at its narrowest point. And right now, the single most consequential piece of geography on Earth for your business.
Since the escalation of the US-Iran conflict in late February 2026, global oil markets have been in crisis mode. Brent crude briefly touched $119.50 per barrel before settling around $90–$94 — with a $100–$110 scenario still very much on the table.
About 20% of the world’s daily crude and gas supply transits through that strait — roughly 15 million barrels a day. The near-total disruption has forced Saudi Arabia, UAE, Iraq, and Kuwait to halt shipments of up to 140 million barrels to international refiners.
The International Energy Agency responded by cutting its 2026 global oil supply forecast by 50%, projecting a plunge of 8 million barrels per day in March 2026 alone.
For India, the damage arrived almost immediately.
Supertanker rates more than doubled to $60,000 per day. Shipping lines imposed war-risk surcharges of $2,000–$3,000 per container. Air cargo capacity through Gulf hubs collapsed by over 90%.
And here’s the number most Indian businesses aren’t thinking about yet: GCC and West Asia account for 14% of India’s total exports and 38% of inward remittances.
This is not a distant geopolitical event. It is a domestic economic shock.
📅 Three Timelines. Three Realities. One Business.
Short-Term → Now to 12 Months: Pain, Price Shocks, and Panic Decisions
This is the phase of rapid input cost inflation. No sector is untouched.
- FMCG: Crude-linked packaging and petrochemicals are 10–15% of input costs
- Paints: Exposure jumps to 20–25%
- Chemicals & textiles: Input prices up 25–30% in the Mumbai-Dombivli belt
- Pharma: APIs up 5–100% depending on the molecule
- Textiles: Finished product prices already up 15%
Short-term stabilisers exist — the IEA releasing 400 million barrels from strategic reserves, OPEC+ adding 206,000 barrels per day, US diplomatic efforts to reopen the Strait. But they buy time, not certainty.
Medium-Term → 1 to 3 Years: Reconfiguration and Reinvestment
If the conflict persists, companies globally will accelerate supply chain diversification. Capital will flow toward energy efficiency, renewable assets, and regional manufacturing.
The World Bank projects that sustained oil market tightness could “curtail supply growth and support a price recovery” by 2027 — meaning the volatility cycle returns, regardless of how this conflict resolves.
The rerouting of global logistics — away from the Strait and the still-disrupted Red Sea — is not a temporary inconvenience. It is reshaping where manufacturing makes economic sense and which countries become preferred sourcing hubs.
Long-Term → 3 to 10 Years: The New Competitive Map
The 2025–2026 period will be remembered as the inflection point where energy security stopped being an ESG checkbox and became a core competitive strategy.
Countries and companies that invested in renewables, green hydrogen, and local energy production during this volatile period will have fundamentally lower, more predictable cost structures a decade from now.
Those that didn’t? They will remain exposed to every next conflict. Every next choke point. Every next spike.
👤 How This Is Changing Your Consumer
The consumer who walked out of 2022–2024 is not the same person.
The inflation years didn’t just change wallets — they changed mindsets.
75% of global consumers maintained their trade-down behaviours even after economic conditions improved in early 2025. Over 70% said they would continue these habits even if their discretionary budgets grew.
This is no longer a response to inflation. It is a new operating system for spending.
Capgemini’s 2026 Consumer Trends report puts it plainly: “Consumers actively compare prices across platforms, look for discounts and loyalty benefits, and trade down to private labels or affordable brands. Loyalty is now conditional, driven by better deals, faster delivery, and personalised rewards.”
What’s happening in each spending category — right now
🟢 Protected (Sticky Spending) Utilities, education, healthcare, rent, insurance. These are the four walls consumers will not breach. If your business is in these categories, demand isn’t your problem — cost management is.
🟡 Food & Grocery (Under Pressure, Not Collapsing) Global FMCG inflation averaged +2.6% in 2025, but health care (+5.4%), snacks (+4.9%), and beverages (+3.6%) are running hot. Consumers are shifting to private labels, smaller packs, and cooking at home. The question FMCG companies in India are now facing: cut grammage or raise prices? Both choices cost you consumer trust.
🔴 Discretionary (Hit Hard) Eating out, entertainment, clothing, home décor, big-ticket durables — all under sustained pressure. Global consumers plan to keep spending less on dining out and food delivery in 2026 — the third consecutive year of this trend. Even high-income consumers are not immune.
🟣 The Premiumisation Paradox Here’s where it gets interesting. Premium is not dead. Generic middle-market is.
Consumers will still pay more — but only when they can clearly justify the purchase to themselves. Premium chocolate struggles when cocoa prices spike. Premium craft gin survives because the emotional reward is concentrated and the ticket is manageable. Gourmet and specialist food categories are projected to grow at a 6.05% CAGR.
The “affordable luxury” concept is quietly winning.
5 Questions Your Customer Is Silently Asking Right Now
Before every purchase, your customer is running this mental checklist. Whether you’ve addressed these answers determines whether they stay or leave.
- “Is this worth it today?” — Value is now a universal filter, not a reaction to inflation
- “Is this brand being honest with me?” — Price hikes attributed to greed erode trust faster than the margin gain is worth
- “Can I get this cheaper, closer, or faster?” — E-commerce price comparison is instant. Private label is expanding. Loyalty is conditional
- “Will this last?” — Reliability is the new premium. Durable, multi-purpose, and versatile products are winning
- “Does this brand share my values?” — 58% of consumers say they will pay more for eco-friendly products, led by millennials and Gen Z
🧠 Part 3 — The Strategic Playbook for Businesses
You have three choices. None of them is neutral.
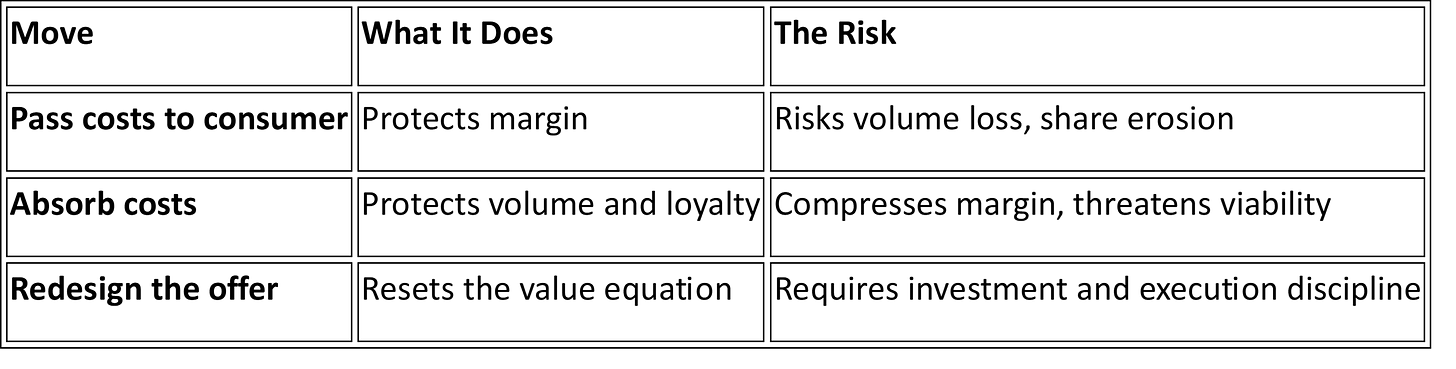
The businesses that navigate this best don’t pick one option. They run all three in parallel — selectively passing on costs where loyalty is high, absorbing selectively in competitive categories, and redesigning the offer to create new value at defensible price points.
Build Pricing Power Before You Need It
This is the most important strategic truth in this entire piece.
Pricing power is built in good times, not borrowed in bad ones.
Apple raises iPhone prices every year — and demand grows — because consumers perceive price as a signal of quality. Dyson charges a premium for vacuum cleaners and maintains margins even as component costs rise, because it has anchored its identity to technological superiority.
For most Indian businesses, the lesson is starker: if your customer doesn’t know why your product is worth more than the alternative, they will leave when you ask them to pay more.
Stop Panic Pricing. Start Dynamic Pricing.
Static annual price lists are a liability in volatile markets.
Winning companies are adopting dynamic pricing models with smart triggers — responding to real-time variables like input costs, competitor moves, and demand signals rather than waiting for the annual budget cycle.
McKinsey’s ADAPT framework offers a structured approach: Adjust discounting. Develop value architecture. Accelerate non-price levers. Plan scenario models. Track performance.
The businesses using data-driven pricing analytics are gaining a compounding advantage over those still relying on instinct and quarterly reviews.
Build a Portfolio Across the Value Spectrum
The bifurcation of consumer markets is a global reality.
High-income segments are consolidating spend on a smaller number of meaningful premium purchases. Value-conscious segments are trading down aggressively. The worst position is a mid-market brand that is neither clearly premium nor clearly affordable. This segment gets attacked from both sides.
Smart businesses are launching tiered portfolios — a “good, better, best” architecture — so that as consumers trade down, they trade within your brand, not out of it.
P&G’s Gillette anchored its value communication on “one refill = 18 shaves” — making cost-per-use tangible and defensible. That’s the kind of messaging that survives inflation.
Localise, Nearshore, and Lock In Your Cost Base
The most durable competitive advantage in this environment is not a clever campaign. It is a supply chain that is structurally insulated from the next Strait of Hormuz closure.
Ask yourself three questions right now:
- What percentage of my input cost is exposed to global freight and energy volatility?
- Which inputs can I source regionally, domestically, or substitute with local alternatives?
- Where am I over-indexed on a single supply country, route, or supplier?
Companies that achieve low-energy, low-distance, low-disruption supply chains can truthfully tell customers: “We are the resilient option in your category.” This is a differentiation story commodity competitors cannot easily replicate.
Nearshoring investment in Europe grew 62% in 2022–2023 compared to 2018–2019. The average capex per nearshoring project tripled to $131 million — indicating that serious businesses are treating this as strategic infrastructure, not a procurement tweak.
🏭 Part 4 — Sector by Sector: Who’s Hit, Who Can Win
FMCG & Consumer Goods Crude-linked packaging costs, petrochemical inputs, and logistics surcharges are creating a multi-front squeeze. FMCG players face 100–150 bps margin compression over the next two quarters if they cannot pass costs through.
Direction: Pack-size innovation over outright price hikes (less damaging psychologically). Invest in loyalty — 57% of global consumers are actively using loyalty points to reduce costs.
Pharmaceuticals India depends on China for 65–70% of its APIs. Glycerine is up 64%. Paracetamol is up 26%. NPPA price controls prevent easy pass-through. Gulf export routes are disrupted.
Direction: This is no longer a procurement problem. It is a strategic survival issue. Backward integration into domestic API manufacturing is now an existential priority.
Textiles & Chemicals Chemical prices up 25–30% in manufacturing belts. Imported coal spiking. Finished product prices up 15%.
Direction: Fast-track energy audits. Explore renewable process heat. Build export relationships in Southeast Asia, Africa, and the UK — away from Gulf dependency.
Automobiles & Auto Components Automakers are considering 2–3% price increases as steel, aluminium, and electronics costs rise. PLI for automobiles generated ₹32,879 crore in sales in FY 2025–26.
Direction: Double down on localisation of EV components. Global OEMs seeking to de-risk from China are actively looking for credible Indian supply partners.
Hospitality, QSR & Food Service Energy costs, food input inflation, and consumer pullback on out-of-home spending create a triple hit.
Direction: Value-engineer your menu around hero SKUs. Invest in kitchen energy efficiency. Move customer relationships from transactional to relational through loyalty apps and membership models.
Jewellery & Luxury Retail Gold rises in conflict — putting cost pressure on jewellers even as discretionary sentiment softens. But high-value jewellery remains a “meaningful premium” purchase among affluent consumers.
Direction: Lead with gold-as-investment narrative. Consider SIP-style buying programmes. In mass-market: lighter-weight, fashion-forward designs that maintain perceived value at lower gram weight.
🇮🇳 Part 5 — The India Opportunity: Unique, Urgent, and Underplayed
Every global crisis reshapes comparative advantage. This one is reshaping it in India’s favour.
Let’s look at what’s actually been built.
India’s PLI Scheme now covers 14 sectors with cumulative investment exceeding ₹2.16 lakh crore, sales of ₹20.41 lakh crore, and exports of ₹8.3 lakh crore. Mobile phone imports have declined by nearly 77% since FY 2020–21; over 99% of domestic demand is now met through local production.
These are not aspirational targets. They are executed outcomes.
The China+1 strategy is back in active discussion, with explicit tailwinds from the India-US trade deal. India’s manufacturing wages are 47% lower than China’s. And India’s position as a supply chain “swing state” — serving as factory floor for Europe, innovation engine for the US, and risk hedge for companies exiting China — creates multi-directional demand.
Where the Opportunities Are
☀️ Renewable Energy Equipment India’s solar manufacturing capacity is set to exceed 125 GW — more than triple domestic demand — creating an export surplus. Energy-importing nations are now treating energy security as a national emergency. India’s timing could not be better.
Under the National Green Hydrogen Mission, India targets 5 million tonnes of green hydrogen production by 2030 with investments of over ₹8 lakh crore — positioning it as a natural export partner for Europe’s decarbonisation needs.pib.gov+1
💊 Pharmaceuticals & APIs India already supplies 20% of global generic medicines. The disruption of Gulf trade routes has created pressure for Gulf nations to diversify pharma procurement — an opening for direct supply chain agreements. PLI for bulk drugs has enabled first-time domestic manufacturing of 191 bulk drugs.theweek+1
📱 Electronics & IT Hardware Mobile phone exports have soared nearly 8x to ₹2 lakh crore. As US-China tariffs keep Chinese electronics at punishing price levels, Indian-manufactured electronics have a pricing window that didn’t exist three years ago.
🌾 Food & Agri-Processing West Asia is a natural market for Indian food exports — historically reliant on Indian rice, spices, processed foods, and FMCG. The conflict has disrupted existing supply chains but also created pressure for Gulf nations to diversify sourcing. India’s food processing PLI — with over ₹9,200 crore invested — is positioned to serve this shift.
🔧 “Resilience as a Service” This is the most innovative framing. India can offer near-shore contract manufacturing, regional cold-chain hubs, and flexible warehousing to global companies seeking to de-risk their supply chains. The narrative writes itself: geographically away from conflict zones. Deep manufacturing capability. Large domestic market. Policy continuity.
For businesses, offering supply chain resilience to international clients converts India’s structural advantages into a differentiated, premium-priced service offering.
📋 Part 6 — What You Must Do Right Now
The Decision Framework: 5 Questions Every Business Must Answer This Week
1. What percentage of my cost base is exposed to energy and freight volatility? Map it precisely. This number tells you your true exposure — and the urgency of your next move.
2. Do I have pricing power with my customers, or am I a commodity? If your customers don’t know why your product is worth more than the nearest alternative, you don’t have pricing power. Start building the brand investment, quality narrative, and loyalty infrastructure now — before you need it.
3. Am I over-indexed on a single supply country, route, or supplier? If more than 40% of a critical input comes from a single geography, you have a structural vulnerability this crisis has just made visible. Start qualifying alternatives immediately.
4. What is my customers’ price elasticity — by SKU, not by category? Not all products in your portfolio have the same elasticity. Data-driven segmentation will show you which products can carry a price increase (high loyalty, low alternatives) and which cannot (commoditised, easily substituted).
5. What is my medium-term investment thesis: efficiency, diversification, or differentiation? Companies that use this crisis to invest in energy efficiency, supply chain localisation, and brand equity will emerge structurally stronger. Those that only defend will face the same crisis again at the next shock.
For Consumers: Spend Smart, Not Just Less
Cutting everything is instinctive. It’s also sub-optimal.
- Protect your productivity — Education, healthcare, and tools that increase your earning capacity are not discretionary
- Shift, don’t sacrifice — Switch to private labels in commodity categories. Cook more at home. Buy durable over disposable
- Support transparent brands — Companies that communicate openly about why prices are rising are worth supporting. They’re building a relationship, not exploiting a moment
- Time your big purchases — Electronics, apparel, and home goods will fluctuate significantly over the next 12 months. If a large purchase is non-urgent, wait 6 months
- Buy Indian where you can — Not nationalism. Pragmatism. Locally manufactured goods carry less geopolitical supply risk, lower freight exposure, and — in PLI-backed categories — often comparable or superior quality
The Bottom Line
The Catch-22 — raise prices and risk your market, absorb costs and risk your business — is not truly unresolvable.
It is resolved by businesses that invest in the preconditions for pricing power: brand equity, operational efficiency, supply chain resilience, and customer loyalty.
Those investments cannot be made in a crisis. They must have been made before it.
The businesses that will thrive over the next three years are not the ones with the lowest prices or the highest margins. They are the ones with the most loyal customers, the most insulated cost structures, and the clearest story about why their product is worth what they charge.
The question is not whether to raise prices or protect margins.
It is whether your business has done the work to deserve both.
If you’re a business owner, brand manager, or senior leader and you haven’t started thinking about these questions — this is your signal.
At Blue Mango Consulting Group, we help businesses navigate exactly this: pricing strategy, supply chain resilience, consumer insight, and market positioning for the India of today and tomorrow.
www.bluemangoconsultinggroup.com
— Kirtiraj Gohil, Founder & CEO, Blue Mango Consulting Group
If this piece was valuable, share it with one business owner who needs to read it today. And if you’re not yet subscribed — you know what to do.